Arkansas Homebuyer Eligibility Checker
Enter your estimated financial details to see which loan programs you might qualify for in Arkansas.
Debt-to-Income (DTI) Calculator
You found the perfect bungalow in Little Rock or a fixer-upper in Fayetteville. You have your down payment saved up, you’ve toured the neighborhood, and you’re ready to make an offer. Then the lender drops the question that stops many aspiring homeowners in their tracks: "What is your credit score?" It’s not just a number; it’s the gatekeeper to your keys. If you are looking to buy a house in Arkansas, understanding the specific credit score thresholds can save you months of frustration and thousands of dollars.
Here is the blunt truth: there is no single magic number. The requirement changes based on who is lending you the money and what kind of loan you choose. A veteran with a 580 score might get approved for one program while a conventional buyer with the same score gets rejected by another bank. This guide breaks down exactly what lenders look for in the Natural State, how different loan types change the math, and what you can do if your score isn’t quite there yet.
The Baseline: What Lenders Actually Look For
Most people assume they need a 700+ score to buy anything. That’s a myth. While higher scores definitely get you better interest rates, the floor for approval is much lower than most think. In Arkansas, as in the rest of the US, lenders use the FICO score model to gauge risk. They aren't just looking at whether you pay bills on time; they are calculating the probability that you will default on a $150,000 to $300,000 debt over the next 30 years.
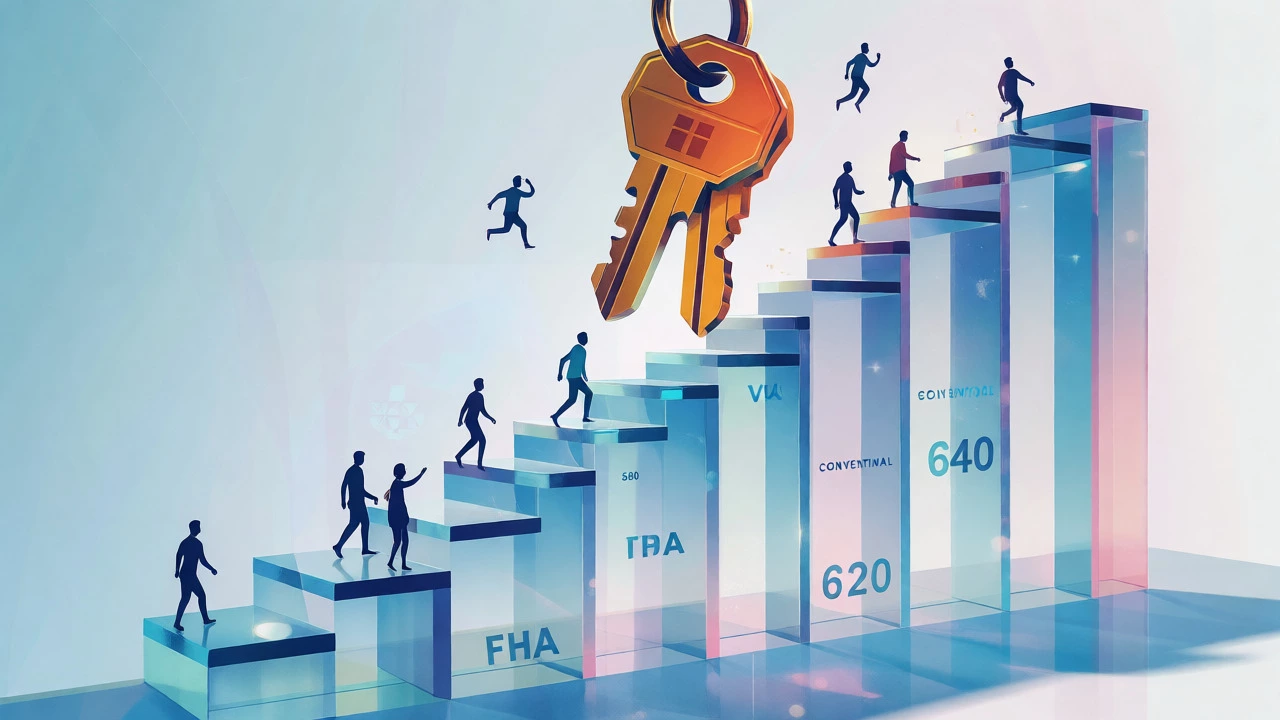
Generally, here is where the lines are drawn:
- Conventional Loans: Typically require a minimum score of 620. Some private lenders may go down to 600, but expect higher fees.
- FHA Loans: Backed by the Federal Housing Administration, these allow scores as low as 580 with a 3.5% down payment. Scores between 500 and 579 are technically eligible but usually require a 10% down payment, which defeats the purpose for many buyers.
- VA Loans: For veterans and active military, there is no official minimum set by the VA itself, but most lenders impose an "overlay" requiring a score of 620 to 640.
- USDA Loans: Ideal for rural Arkansas properties, these often accept scores down to 640 via automated underwriting systems, though manual approvals can happen lower.
Notice the pattern? The government-backed loans (FHA, VA, USDA) are more forgiving because the government guarantees part of the loan. Conventional loans are riskier for banks, so they demand stricter proof of reliability.
Why Your Location in Arkansas Matters
Does living in Fort Smith versus Bentonville change your credit requirements? Not directly. However, location affects the type of loan available to you, which indirectly impacts your credit needs. For instance, USDA Rural Development loans are strictly for homes in designated rural areas. Parts of Northwest Arkansas are booming and suburban, potentially disqualifying those homes from USDA benefits. Meanwhile, vast stretches of Eastern and Southern Arkansas qualify for USDA programs, offering zero-down financing to borrowers with moderate credit scores.
Additionally, state-specific assistance programs play a huge role. The Arkansas Housing Authority offers down payment assistance programs that often pair with FHA loans. These programs frequently have their own credit guidelines, sometimes accepting scores as low as 580 if you complete a homebuyer education course. Ignoring these local resources means missing out on help specifically designed for Arkansas residents.
Decoding the Loan Types: Which One Fits Your Score?
To give you a clear picture, let’s compare the main options side-by-side. This table highlights the trade-offs between credit flexibility and upfront costs.
| Loan Type | Minimum Credit Score | Down Payment | Mortgage Insurance | Best For |
|---|---|---|---|---|
| FHA | 580 (500-579 w/ 10% down) | 3.5% | Required for life of loan (if <10% down) | First-time buyers, lower credit |
| Conventional | 620+ | 3% - 20% | Dropped at 20% equity | Better credit, avoiding PMI long-term |
| VA | No official min (Lenders ~620) | 0% | None | Veterans, Military Spouses |
| USDA | ~640 (Automated Underwriting) | 0% | Guarantee Fee + Annual Fee | Rural properties, income limits apply |
If your score is hovering around 600, you are in a tricky spot. You likely don’t qualify for the best conventional rates, but you might be too high for some aggressive subprime programs. This is where FHA shines. It bridges the gap. But remember, FHA loans come with Mortgage Insurance Premiums (MIP) that stick around for the life of the loan unless you put 10% down. That extra monthly cost adds up. Over 30 years, paying MIP could cost you tens of thousands of dollars compared to a conventional loan where insurance drops off once you hit 20% equity.
Beyond the Number: Debt-to-Income Ratio
A 620 credit score won’t save you if your debt-to-income (DTI) ratio is a mess. Lenders calculate DTI by dividing your total monthly debt payments by your gross monthly income. Most Arkansas lenders want this number below 43%, though FHA allows up to 50% in certain cases with compensating factors like significant cash reserves.
Imagine you earn $4,000 a month. If you have a car payment of $400, student loans of $300, and credit card minimums of $100, your debt is $800. Your DTI is 20%. That looks great. But add a potential mortgage payment of $1,500, and your new DTI jumps to 57.5%. Now you are over the limit. Before you worry about your credit score, pay down those revolving debts. Lowering your DTI can sometimes compensate for a slightly lower credit score during manual underwriting.
How to Boost Your Score Quickly in Arkansas
Do you need to wait two years to buy? Not necessarily. If your score is in the 500s or low 600s, you can often improve it significantly in 3 to 6 months with targeted actions.
- Check for Errors: Pull your reports from Equifax, Experian, and TransUnion. Dispute any incorrect late payments or accounts that aren’t yours. Removing one error can boost your score by 20-50 points.
- Pay Down High-Balance Cards: Utilization matters. If you have a $1,000 limit and owe $900, that’s 90% utilization-a red flag. Paying it down to $300 (30%) can instantly raise your score.
- Don’t Close Old Accounts: Length of credit history helps. Keep your oldest credit cards open, even if you rarely use them.
- Use Rent Reporting Services: Some services report your rent payments to credit bureaus. If you’ve been paying rent on time in Arkansas for years, this data might already be helping you, or you can start reporting it now to build history.
Avoid opening new credit lines right before applying. Every hard inquiry knocks a few points off your score temporarily. Wait until after closing to buy that new truck or furniture.
The Role of Local Housing Programs
Many buyers overlook state-level assistance. The Arkansas Development Finance Authority (ADFA) manages several programs that assist low-to-moderate-income households. Their "House Plus" program, for example, provides down payment assistance funds that act as a second lien. Because these funds are often deferred, they don’t count against your DTI in the same way a traditional second mortgage would.
Furthermore, some counties in Arkansas have specific housing authorities that offer grants for first-time buyers. These grants often come with relaxed credit standards because the goal is community stabilization rather than pure profit. Check with your county’s housing authority website or call them directly. A five-minute phone call could reveal a grant that waives the need for a perfect credit score.
Common Pitfalls That Kill Deals
You got pre-approved! Great. But then you bought a couch on a credit card three weeks before closing. Boom-deal dead. Changes to your financial profile during the underwriting process can trigger re-evaluation. If your score drops below the threshold, the loan is denied.
Another pitfall is assuming all lenders are the same. One bank might reject a 620 score due to internal overlays, while another accepts it. Shopping around doesn’t hurt your score if you do it within a 14-day window (credit scoring models treat multiple mortgage inquiries in a short period as a single inquiry). Talk to at least three lenders. Ask them explicitly: "What is your absolute minimum credit score for an FHA loan in Arkansas?" Get it in writing.
Final Thoughts on Getting Approved
Buying a house in Arkansas doesn’t require perfection. It requires preparation. If your score is below 600, focus on fixing errors and reducing balances. If you are between 600 and 640, target FHA or USDA loans and look into ADFA assistance. If you are above 640, you have leverage to negotiate better rates.
Start early. Credit repair takes time, but not as long as you think. Gather your documents, check your reports, and talk to a local lender who understands Arkansas-specific programs. Your key to homeownership is closer than you think.
Can I buy a house in Arkansas with a 500 credit score?
Yes, but it is difficult. FHA loans technically allow scores as low as 500, but you must put down at least 10% of the purchase price. Many lenders also impose their own minimums, often refusing applications below 580 regardless of down payment size. You will likely face higher interest rates and stricter scrutiny of your employment history.
Does having student loans affect my ability to buy a house in Arkansas?
Yes, primarily through your debt-to-income (DTI) ratio. Lenders count your monthly student loan payment as debt. If your DTI exceeds 43% (or 50% for some FHA loans), you may struggle to qualify. However, if you have a strong credit score and large cash reserves, lenders may overlook a higher DTI.
Are there special programs for first-time homebuyers in Arkansas?
Yes. The Arkansas Housing Authority and the Arkansas Development Finance Authority (ADFA) offer down payment assistance programs. These often include grants or forgivable loans that help cover down payment and closing costs. Eligibility depends on income limits and completing a homebuyer education course, but credit score requirements are often more flexible than standard conventional loans.
How long does it take to improve a credit score enough to buy a house?
You can see improvements in 30 to 90 days by correcting report errors and lowering credit card utilization. For larger jumps (e.g., from 550 to 640), it typically takes 6 to 12 months of consistent on-time payments and debt reduction. Rapid rescore options exist but cost money and are used sparingly by lenders.
What is the average credit score needed for a conventional loan in Arkansas?
The minimum is generally 620, but to get competitive interest rates, aim for 740 or higher. Scores between 620 and 680 are considered "fair" and will result in higher interest rates, increasing the total cost of the loan over its lifetime.